There’s a specific kind of cold sweat that hits you somewhere around your 40th birthday.
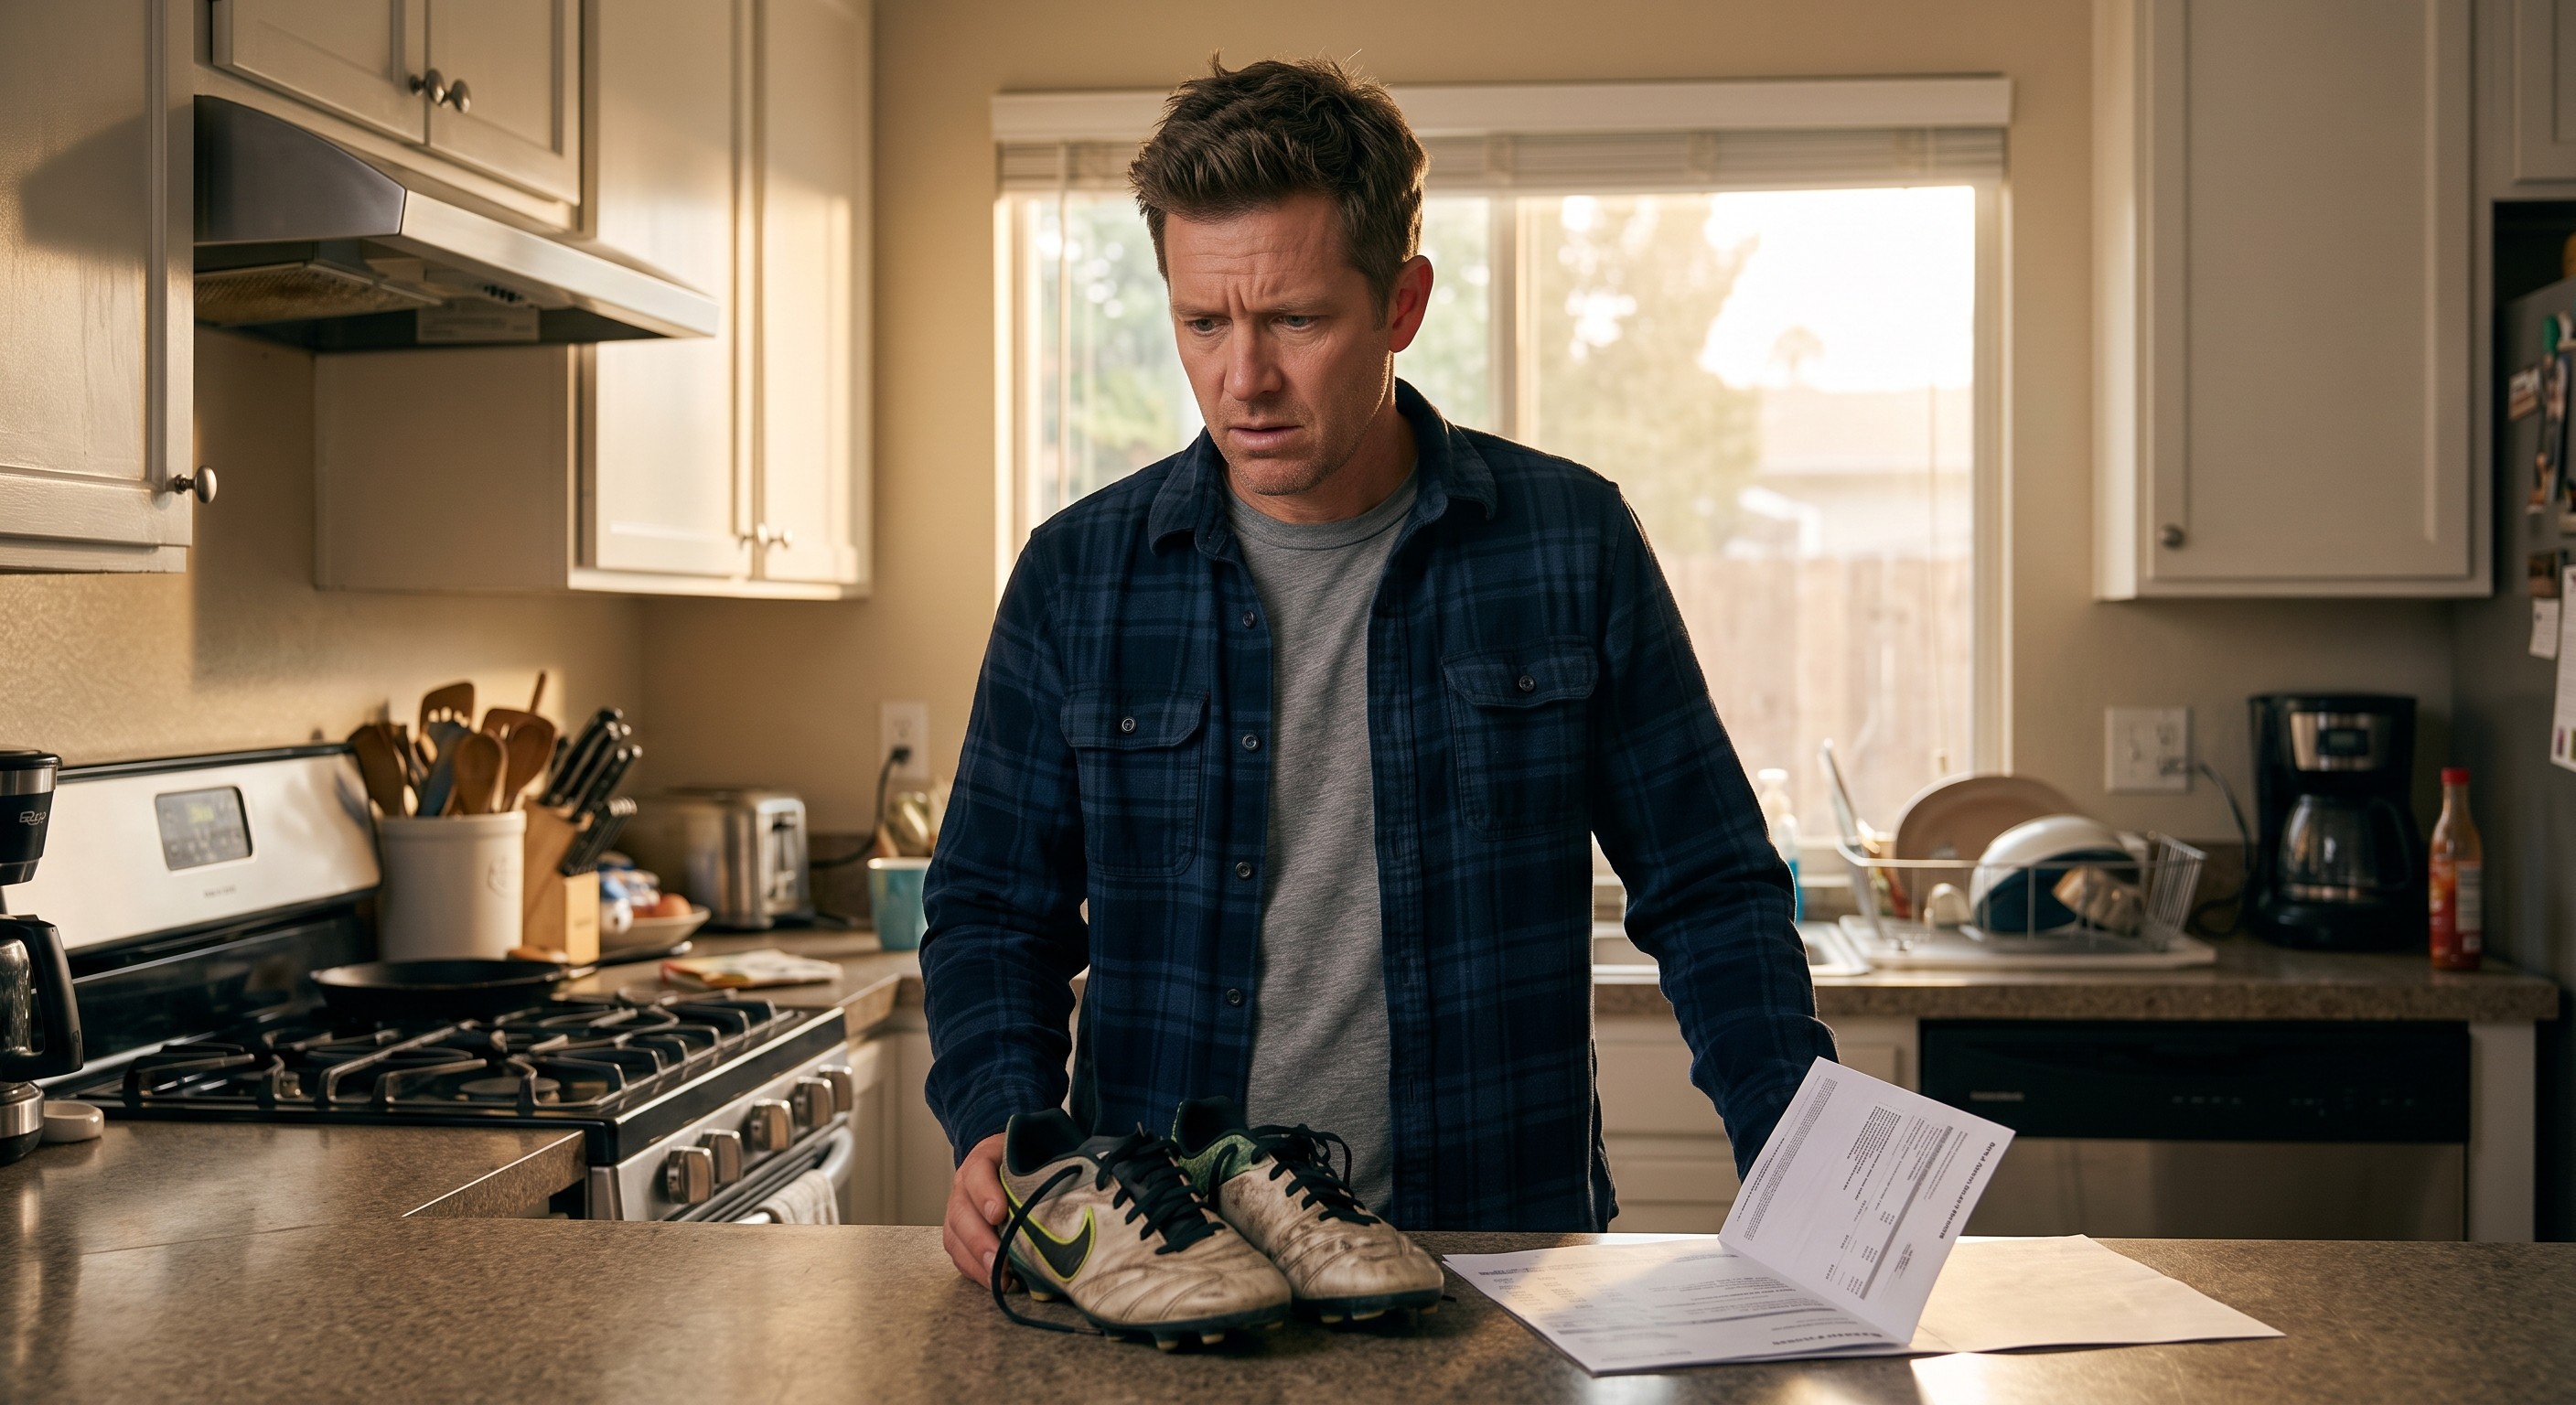
For me, it wasn’t triggered by finding a gray hair or realizing I couldn't paddle out for a three-hour surf session without my shoulders screaming the next day. It hit me standing in the kitchen, holding a pair of my 12-year-old’s soccer cleats that he’d outgrown in exactly four months.
I looked at the cleats, looked at my mortgage statement, and then looked at a standard savings account that was losing a slow, agonizing war to inflation.
It’s the realization that you’re suddenly the adult in the room. You have a family, a legacy to build, and a runway that isn't infinite anymore. If you’re a guy in your 40s who just woke up to the fact that you aren't financially versed, your brain treats this realization like an acute stress response.
And that’s exactly when most guys make their first critical mistake: They panic.
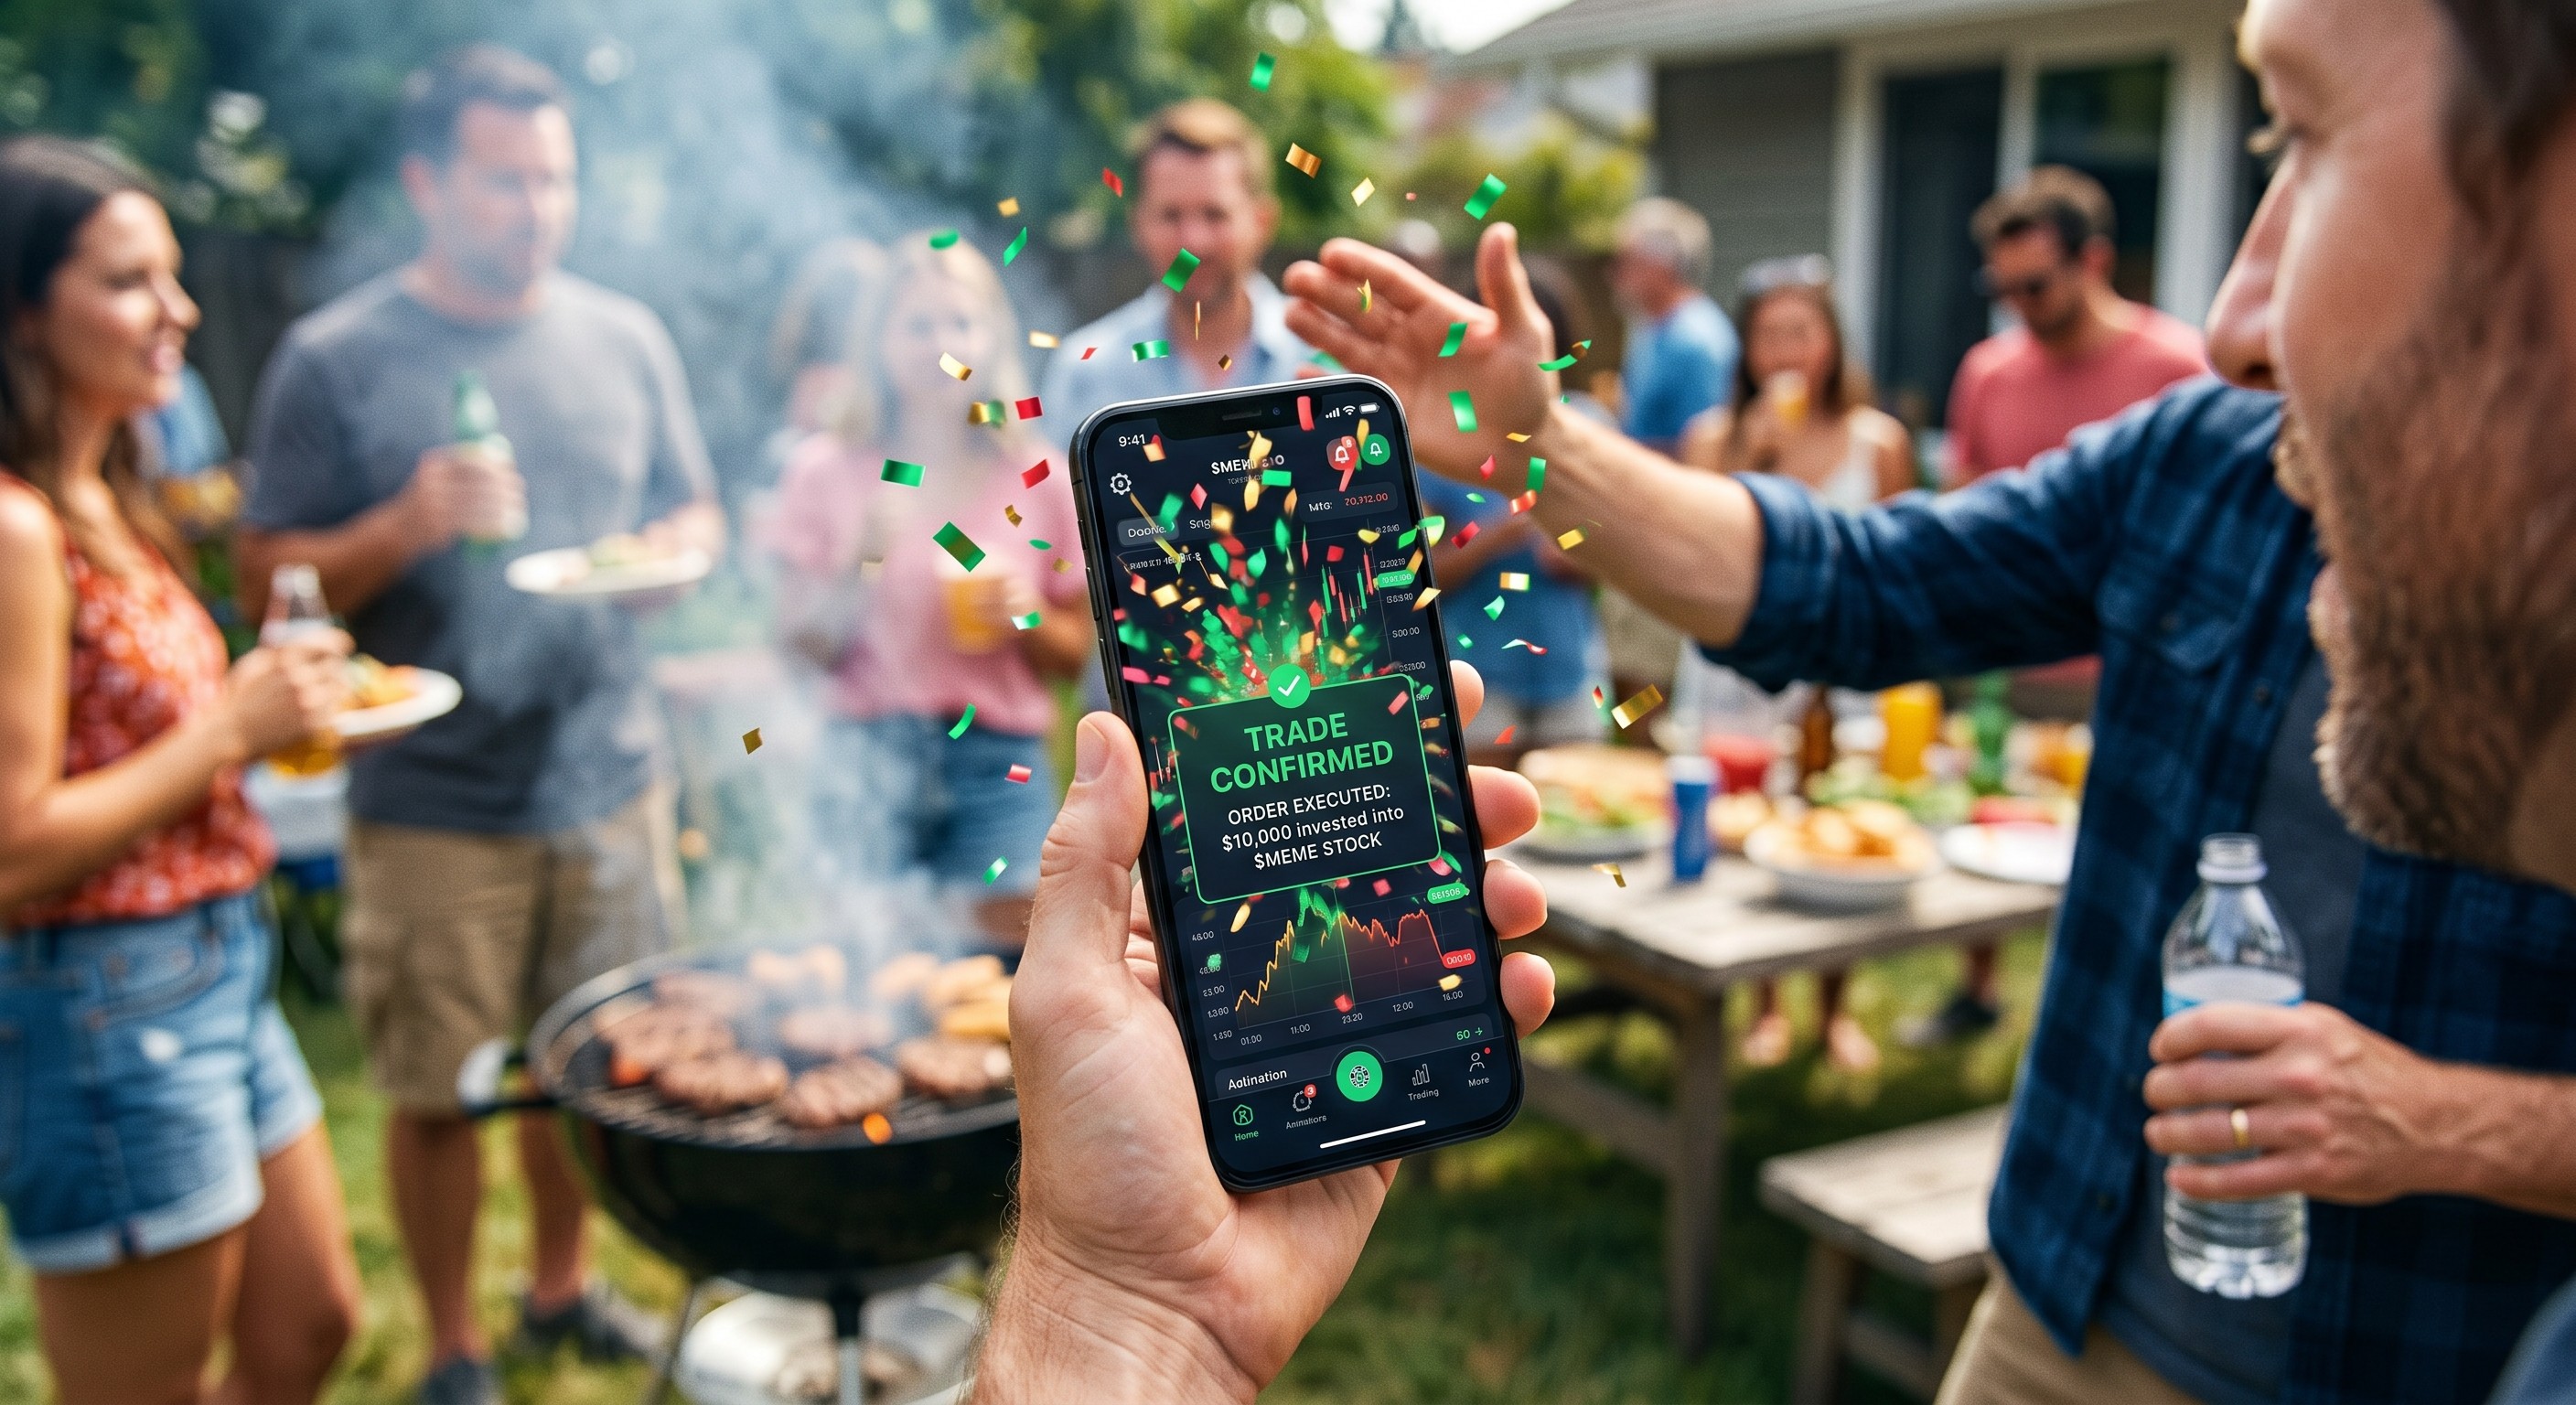
They try to make up for lost time by doing something drastic. They download a flashy app with confetti animations, throw half their liquidity into whatever meme stock their buddy mentioned at a barbecue, and try to trade options on their phone while hiding in the bathroom.
Let’s take a breath, step back, and look at the vitals. When you wipe out at 40, your joints take longer to heal. We don’t paddle into a hurricane on day one. Here is the clinical, low-drag blueprint for getting your financial house in order—and actually learning how the machinery works along the way.
Step 1: Stop the Bleed (The 90% Baseline)
In emergency medicine, you don't worry about cosmetic stitching until you’ve stopped the bleeding. In finance, this means treating your high-interest debt and anemic cash accounts like a trauma case.
Before you buy a single share of anything, you need an emergency reserve parked in a high-yield cash account or short-term sovereign paper. Once that’s stabilized, we build the bedrock.
The core operating strategy is the 90/10 Split.
Exactly 90% of your investable capital goes into the "Set-and-Forget" bucket. This is your family’s life raft. It goes into broad-market index funds (total US market and international blends) inside tax-advantaged shells like your 401(k), Roth IRAs, and 529 plans for those kids growing out of their shoes.
For this bucket, you want a boring, clinical broker platform. Legacy institutions like Fidelity, Vanguard, or Charles Schwab—places with zero maintenance fees, automated dividend reinvestment (DRIP), and an interface that actively discourages you from checking it every ten minutes. You want this money compounding in the background like an IV drip: quiet, efficient, and out of sight.
Step 2: The "Tuition Fund" (The 10% Active Core)
Now, I could tell you to just index 100% of your money and go back to sleep. Mathematically, it’s a sound diagnosis. But let’s be honest: you’re here because you want to understand money. You want financial literacy so you can pass it down to your kids. Pure passive investing is like watching paint dry in a sterile room. It works, but it doesn't teach you how to surf the market.
That’s where the remaining 10% comes in. This is your Active Tuition Fund.
This is not play money. It is not for gambling on 0DTE options gamma traps. It is clinical research with hard stop-losses. You use this 10% to learn how order flow toxicity works, how to read an SEC 10-K balance sheet, and how to execute controlled swing trades.
Think of it like an offshore wave: the reef (your 90% bucket) handles the deep, heavy ocean swell. But you work the inside break with a smaller board (your 10% bucket) to hone your balance, entries, and timing.
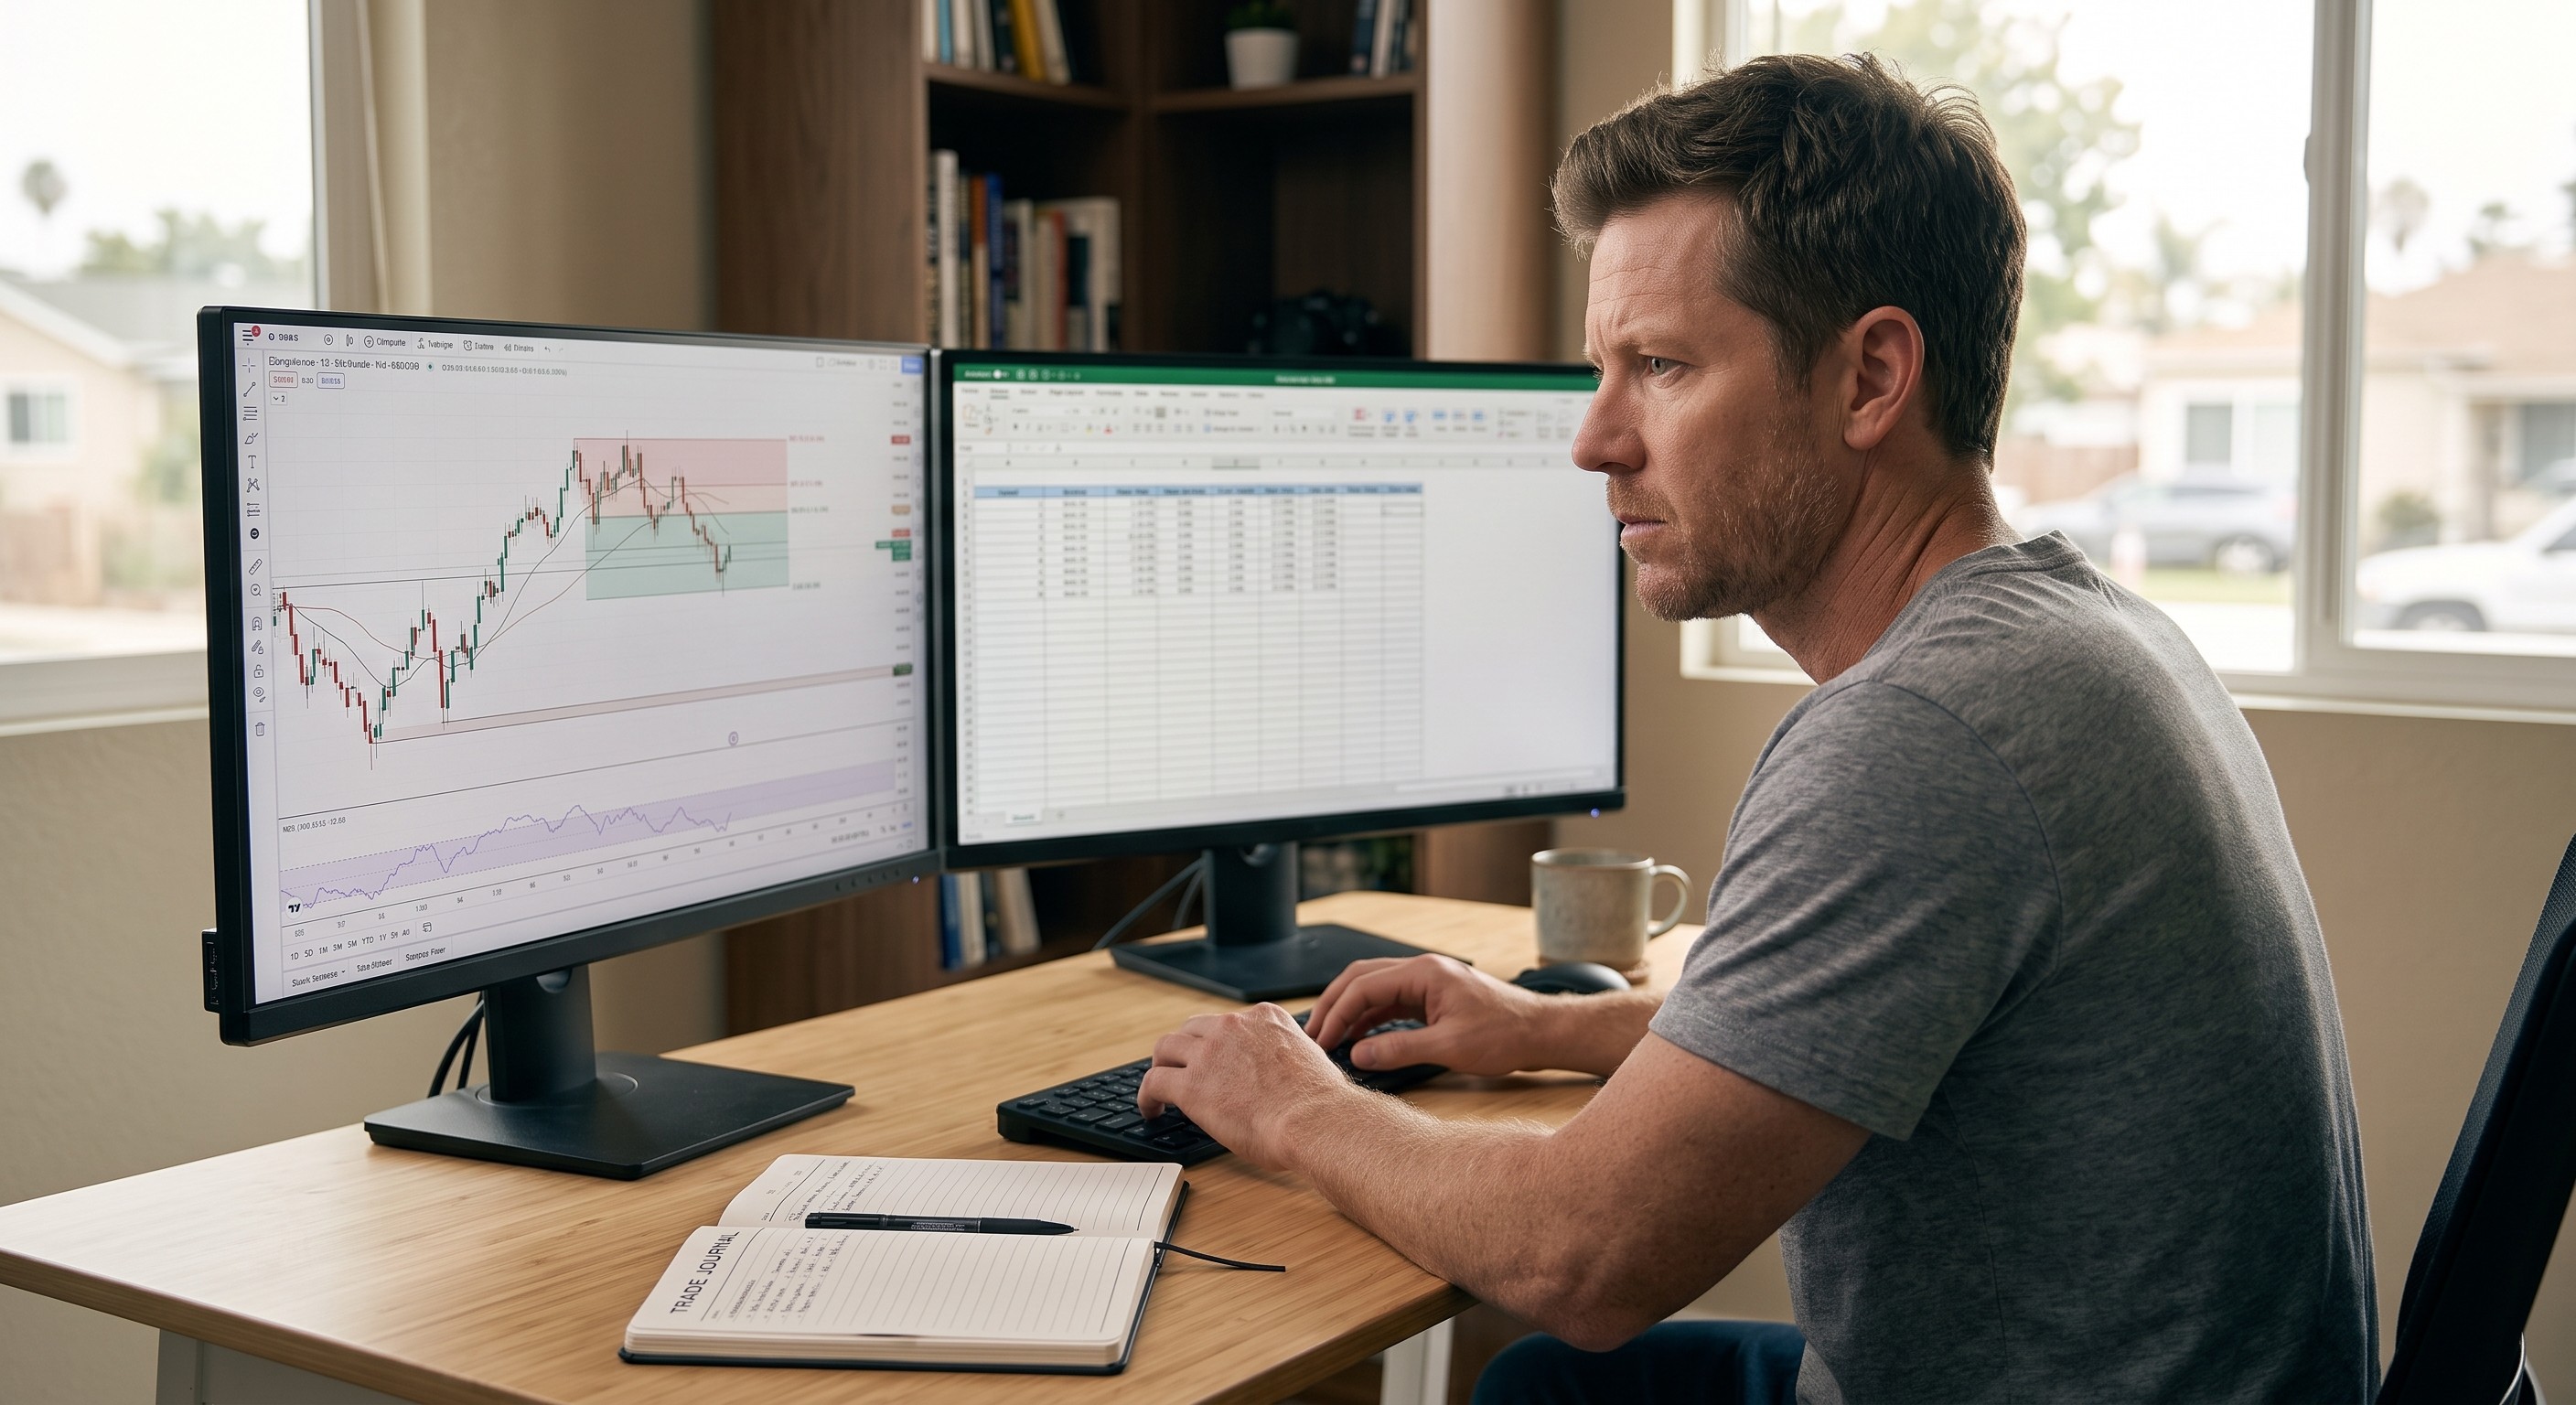
Step 3: Picking the Right Gear
If you are going to actively manage that 10%, your choice of broker matters immensely. Checking your portfolio twelve times during your kid’s soccer match isn't active investing; it's a symptom of a bad platform designed to harvest your attention.
If you aren't sure where your style fits yet, run your numbers through our automated Broker Match Quiz. Otherwise, when scouting a platform for your active account, stick to this triage checklist:
Broker Triage Checklist
- Zero Gamification: If the mobile app shoots off digital fireworks when you place an order, delete it. You want an interface that looks like a medical diagnostic monitor, not a slot machine.
- Verified Paper Trading: A quality broker lets you practice with simulated equity first. You wouldn't perform surgery without doing a residency; don't trade live capital until you've tested your thesis in a sandbox. Desks like Interactive Brokers or Tastytrade lead the sector here.
- Execution Transparency: Scrutinize the order routing fine print. Are they skimming your fills via wholesale sub-penny internalization or aggressive Payment for Order Flow (PFOF)? Insist on a platform that prioritizes direct lit routing over marketing slogans.
Building wealth in your 40s isn't about catching lightning in a bottle. It’s about procedural discipline. It’s about setting up a 90% baseline that protects your family from your own ego, and a 10% exploration fund that sharpens your financial mind.
The market is a big ocean. It’ll be there tomorrow. Get your baseline set, grab a coffee, and I’ll see you out in the lineup.